Best Automotive CRM Software for Car Dealerships
Find the best automotive CRM for your dealership. Compare 13 platforms by rooftop pricing, DMS integration, ratings, and FTC compliance for 2026.
Contact Us
We implement CRM for franchise groups, independent lots, and OEM distributors. Across those projects one pattern repeats: dealers shop for CRM features first and discover the DMS integration problem second, usually after they sign.
That order is backwards. Your Dealer Management System decides which CRMs can actually read your repair orders, push a deal jacket, and write a solid unit back without a nightly CSV. Pick the CRM before you check that, and you buy a lead manager that sits next to your DMS instead of inside your operation.
This guide fixes that order. It covers dealership-native and horizontal CRM platforms for OEM and fleet operations second, and the compliance layer that most comparison articles skip entirely.
Key Takeaways
How We Evaluated 13 Automotive CRM Platforms: Six Scoring Criteria
We scored each platform on six criteria that come from implementation work, not from vendor decks.
DMS Integration Depth
Certified bidirectional interface, read-only pull, or flat-file import. A certified bidirectional interface writes deals and customers back into the DMS. A flat-file import does not, and it breaks whenever the DMS changes a column.
Lead Ingestion
Native ADF/XML parsing, OEM lead feed handling, and duplicate detection against existing customer records. ADF (Auto-lead Data Format) remains the standard wrapper for third-party leads from marketplaces and OEM programs. A CRM that cannot parse ADF cleanly will mangle every lead from your listing sites.
Deal-Side Capability
Desking, payment calls, F&I product presentation, and credit integration through RouteOne, Dealertrack, or 700Credit.
Equity Mining
Whether the platform reads DMS service history and open lender payoff data to surface upgrade candidates, or whether you bolt on AutoAlert separately.
Verified User Ratings
G2 and Capterra scores with review counts, because a 4.6 rating on 4 reviews carries no weight against a 4.2 on 109.
Total Cost Across Three Years
License plus implementation plus DMS data-access fees plus messaging.
Automotive CRM Comparison Table: Pricing, DMS Integration, and User Ratings
| Platform | Owner | Best Fit | DMS Integration | Reported Street Price | Rating (Reviews) |
|---|---|---|---|---|---|
| VinSolutions Connect | Cox Automotive | Franchise groups on Cox products | Deep, Cox ecosystem | $500 to $3,000/rooftop/mo | 4.2 G2 (109) |
| CDK Elead | CDK Global | Enterprise groups on CDK Drive | Native CDK Drive | $800 to $2,500/mo | 4.4 G2 (76) |
| DriveCentric | DriveCentric | Stores with adoption problems | API-based | $700 to $2,200/mo | 4.6 G2 |
| DealerSocket | Solera | Mid-size, broad feature set | Native to Solera DMS | $750+/mo | 3.8 G2 (65) |
| Tekion CRM | Tekion | Cloud-native groups | Native Tekion ARC | Bundled with DMS | 4.4 G2 (13) |
| ProMax | ProMax | Special finance and BHPH | Standard interfaces | $800 to $2,500/mo | Not rated on G2 |
| AutoRaptor | AutoRaptor | Independent and BHPH | Standard interfaces | $500 to $1,500/mo | 4.6 Capterra (274) |
| Selly Automotive | Selly | Budget, mobile-first independents | Light | Low tier | 94% satisfaction |
| PBS Systems | PBS | Canadian rooftops | Native PBS DMS | Not published | Not published |
| Dabadu XRM | Dabadu | Canadian independents | API-based | Not published | 5.0 G2 (129) |
| Dynamics 365 Sales | Microsoft | OEM, distributor, fleet | Via Fortellis or custom | $8 to $150/user/mo | 3.8 G2 (1,600+) |
| Salesforce Sales Cloud | Salesforce | Multi-brand enterprise groups | Custom via MuleSoft | $25 to $550/user/mo | 4.4 Capterra (18,785) |
| Zoho CRM | Zoho | Small independent operations | Flat file or API | $14 to $52/user/mo | Varies by tier |
Ratings pulled from G2 and Capterra listings as published through August 2026. Street pricing reflects ranges reported by dealers, since most automotive CRM vendors quote per rooftop and publish nothing.
Which Automotive CRM Integrates With Your DMS: CDK Drive, Reynolds, Tekion, Dealertrack, and PBS
Every dealership CRM reaches your DMS through one of three routes, and the route determines what the CRM can do.
Certified Bidirectional Interface
The DMS vendor publishes an API program, certifies the CRM, and allows writes. CDK runs this through Fortellis. Reynolds and Reynolds run RCI (Reynolds Certified Interface). Tekion exposes its Automotive Retail Cloud APIs. Dealertrack runs Opentrack.
A certified interface lets the CRM pull repair orders, read deal jackets, and write sold customers back. It also carries a monthly data-access fee that the DMS vendor bills you, not the CRM vendor.
Read-Only Pull
The CRM reads customer and service data but cannot write. Equity mining still works. Deal writeback does not, so your desk manager rekeys every sold unit.
Flat-File or Polling Integration
Scheduled CSV or FTP drops. It works, it costs less, and it breaks on schema changes. Acceptable for a two-rooftop independent, not for a group running one customer record across stores.
Practical Shortlist by DMS
Ask every vendor one question and get the answer in writing: is this a certified bidirectional interface, what does the DMS vendor charge monthly for it, and who owns the data if we leave?
Best Dealership-Native CRM Platforms: VinSolutions, Elead, DriveCentric, DealerSocket, Tekion, ProMax, and AutoRaptor
1. VinSolutions Connect CRM - Deepest Data, Heaviest Interface
Cox Automotive owns VinSolutions, which puts it in the same data estate as Dealertrack, vAuto, Kelley Blue Book Instant Cash Offer, and Autotrader. That matters operationally. Connect Automotive Intelligence scores leads against shopper behavior observed across Cox marketplaces, so the scoring model sees activity that happened before the lead ever reached your store.
The platform handles desking, equity mining through service and payoff data, and service-to-sales handoff inside one record. Reporting depth beats every competitor on this list, which is why sales managers defend it and salespeople complain about it.
Strengths
Weaknesses
Fit
Franchise groups already running Dealertrack, vAuto, or Autotrader. Skip it if your store already abandoned one complex CRM.
2. CDK Elead - The Enterprise Choice Inside CDK
Elead sits natively on CDK Drive, and that native position is the whole argument. No Fortellis layer, no third-party integration fee, no sync lag on the deal jacket.
Elead built its reputation on BDC process management. Call scripting, task escalation, and manager queue oversight are genuinely stronger here than in most competitors, which is why large groups running centralized BDCs standardize on it.
Strengths
Weaknesses
Fit
Groups running CDK Drive across five or more rooftops with a centralized BDC.
3. DriveCentric - The Adoption Fix
DriveCentric solves a different problem from the two above. It does not try to out-report VinSolutions. It tries to get your salespeople to actually open the CRM.
Video messaging sits inside the workflow rather than bolted on. The Genius AI layer drafts responses, handles after-hours engagement, and re-engages aged leads. Rep-facing design consistently draws the highest satisfaction scores in the category.
Strengths
Weaknesses
Fit
Stores where the last CRM failed on adoption rather than capability.
4. DealerSocket - Broadest Single-Vendor Suite
Solera owns DealerSocket, and it remains the widest all-in-one option: CRM, inventory management, desking, websites, and equity mining under one contract and one support line.
Revenue Radar handles equity mining natively, which removes the AutoAlert line item for many stores.
Strengths
Weaknesses
Fit
Mid-size independents that want to reduce vendor count more than they want best-in-class in any single category.
5. Tekion CRM - Cloud-Native, If You Commit to the Platform
Tekion Automotive Retail Cloud rebuilt the DMS as a modern cloud platform, and the CRM is a module inside it rather than a separate product. That architecture removes the integration problem entirely: there is no interface, because there is no second system.
The tradeoff is total. You cannot run Tekion CRM meaningfully without Tekion DMS.
Strengths
Weaknesses
Fit
Groups already migrating off legacy DMS, or new rooftops with no migration debt.
6. ProMax - Special Finance and Desking
ProMax serves the credit-challenged buyer better than anything else on this list. Deal Finder matches credit profiles against live inventory and lender programs, so the desk works from what a customer can actually get approved on rather than what they walked in asking about.
Compliance tooling covers OFAC screening, Red Flags Rule identity verification, and adverse action notices, which matters when subprime volume brings regulatory exposure with it.
Strengths
Weaknesses
Fit
BHPH operations and franchise stores with meaningful special finance volume.
7. AutoRaptor - Transparent Pricing for Independents
AutoRaptor carries the strongest verified review base for independent dealers at 4.6 on Capterra across 274 reviews, which is a more meaningful signal than most scores in this category.
It unifies text, call, and email in one inbox with automatic activity logging, and it prices transparently with unlimited users, which removes the seat-counting problem that kills small-store CRM budgets.
Strengths
Weaknesses
Fit
Independent lots and small groups running one to five rooftops.
8. Selly Automotive and the Budget Tier
Selly targets mobile-first independent dealers who need texting, call recording, and lead follow-up without enterprise overhead. It will not desk a complex deal or mine equity against service history. For a small used-car operation running 30 to 60 units a month, it covers the actual workflow.
9. Canadian Rooftops - PBS Systems, Activix, Dabadu XRM
Canadian dealers face a different stack. PBS Systems runs roughly 3,500 Canadian rooftops with bilingual support and PIPEDA-aligned data handling. Activix serves Quebec strongly. Dabadu XRM holds a 5.0 G2 rating across 129 reviews.
If you operate in Canada, evaluate these before the American platforms. Bilingual compliance and provincial privacy law will drive the decision more than feature parity.
Horizontal CRM Platforms for OEM, Distributor, and Fleet Operations
These four are not dealership CRMs. They become the right answer when your business extends past retail: an OEM importer managing a dealer network, a fleet leasing operation, a multi-brand group consolidating customer data across non-automotive lines.
10. Microsoft Dynamics 365 Sales
Microsoft Dynamics 365 licenses per user across four tiers. Sales Premium bundles 1,000 Copilot credits per user per month, and Microsoft Relationship Sales adds LinkedIn Sales Navigator.
Pricing
One correction worth stating plainly, because most automotive CRM articles repeat it: the Dynamics 365 Automotive Accelerator is a 2019 to 2020 era industry data model built with partners including Annata, and its public repository has seen no meaningful activity since 2022. Treat it as a reference schema for a custom build, not as a shipping automotive product. The current Microsoft automotive story runs through Copilot, Dataverse, and partner ISV solutions such as Annata 365.
Fit
OEM importers, distributor networks, and dealer groups already standardized on Microsoft 365, Power BI, and Azure.
Reality Check
Dynamics holds a 3.8 G2 rating across 1,600+ reviews. Implementation for a dealer network runs $25,000 to $100,000 and up, and the license is the smallest line in that budget.
11. Salesforce Sales Cloud
Salesforce raised list pricing in late 2025.
Pricing
Note the branding shift, because it matters for what you are buying. Einstein was the predictive layer. Agentforce is the current agentic layer, and Agentforce 1 Sales is where the autonomous follow-up and qualification capability now sits. Buying Enterprise and expecting the agent capability is a common and expensive misread.
Salesforce Automotive Cloud exists as a separate industry product with vehicle, driver, and household data models built in. Evaluate that rather than generic Sales Cloud if you go this route.
Fit
Multi-brand enterprise groups, captive finance arms, and OEM operations with in-house development capacity.
12. HubSpot Sales Hub
HubSpot pricing gets misquoted constantly, including in the version of this article we published previously. The $890 and $3,600 figures belong to Marketing Hub, not to the CRM.
Pricing
HubSpot has no automotive data model, no desking, no ADF parsing, and no DMS interface. It handles marketing automation and pipeline well, which makes it a reasonable fit for a dealer group's marketing operation running alongside a dealership CRM, not a replacement for one.
13. Zoho CRM
Zoho holds USD pricing steady through 2026, with monthly billing running roughly 20 to 34 percent higher than annual. Zia AI agents now appear as low as Standard, with the full sales assistant landing on Enterprise.
Pricing
Blueprint gives you visual process enforcement, which handles a standardized sales process well at a low price point. You will build the automotive layer yourself.
Fit
Small independent operations under 10 users with a simple process and no DMS writeback requirement.
Feature Comparison: What Actually Separates These Platforms
| Capability | VinSolutions | Elead | DriveCentric | DealerSocket | ProMax | AutoRaptor |
|---|---|---|---|---|---|---|
| Desking and payment calls | Strong | Strong | Moderate | Strong | Strongest | Basic |
| Equity mining | Native | Native | Partner | Revenue Radar | Deal Finder | Partner |
| BDC process management | Strong | Strongest | Moderate | Strong | Moderate | Moderate |
| F&I and credit integration | RouteOne, Dealertrack | RouteOne, Dealertrack | Partner | RouteOne | 700Credit native | RouteOne |
| Native video messaging | No | Limited | Yes | No | No | No |
| AI engagement layer | Connect AI | Elead AI | Genius AI | Limited | Limited | Native AI |
| Service-to-sales handoff | Strong | Strong | Moderate | Strong | Moderate | Basic |
FTC Safeguards Rule and A2P 10DLC Requirements for Dealership CRM Software
Two regulatory requirements now constrain which CRM you can legally operate. Neither appears in most comparison guides.
FTC Safeguards Rule
The FTC treats dealerships as financial institutions under the Gramm-Leach-Bliley Act, because you arrange financing. That makes the Safeguards Rule binding, and compliance deadlines have already passed.
Your CRM holds nonpublic personal information: credit applications, social security numbers, income data. The Rule requires:
Ask every vendor for their SOC 2 Type II report, their encryption standard, their MFA enforcement policy, and their breach notification SLA. Get it before you sign, not during your first audit.
A2P 10DLC Registration for CRM Texting
Every CRM on this list sends text messages. In the United States, application-to-person messaging over 10-digit long codes now requires registration with The Campaign Registry, including brand registration and use-case campaign approval. Unregistered traffic gets filtered or blocked by carriers.
Ask: does the CRM handle 10DLC registration for you, does it pass through carrier fees, and what throughput tier does your brand qualify for? A dealership sending 3,000 messages a day on an unregistered or low-tier campaign will watch delivery rates collapse and never learn why.
TCPA consent requirements also continue to shift through FCC rulemaking and federal litigation. Confirm current requirements with your counsel rather than with a vendor sales rep.
Data Portability and Business Continuity
The June 2024 CDK Global cyberattack halted operations at roughly 15,000 dealerships and made one question permanent in every CRM contract review: what happens to your customer data when the vendor goes dark?
Write these into the contract:
What AI Actually Does in a Dealership CRM in 2026
Vendors all claim AI. The capability splits into four distinct layers, and knowing which one you are buying prevents disappointment.
Predictive Scoring
Ranks leads by close probability. Every platform here does this. Table stakes.
Generative Drafting
Writes response copy that a human sends. DriveCentric Genius, Elead AI, and Zia all sit here.
Agentic Engagement
Responds, qualifies, and books appointments without a human in the loop. Salesforce Agentforce 1 Sales, DriveCentric Genius, and AutoRaptor's AI layer operate here. This is where the capability gap is widest and where the pricing jumps hardest.
Conversation Intelligence
Transcribes and scores phone calls against your process. Dynamics 365 Sales Enterprise includes it. Most dealership CRMs still require a partner such as CallRevu or Car Wars.
One caution on agentic AI in a dealership: an autonomous agent texting a customer about financing terms creates both TCPA exposure and advertising compliance exposure. Define the escalation boundary before you turn it on.
How Much an Automotive CRM Costs Per Rooftop Over Three Years
License price is roughly 30 to 40 percent of your real spend. Budget these lines:
| Cost Line | Typical Range |
|---|---|
| CRM license (per rooftop, dealership-native) | $500 to $3,000/month |
| DMS data-access fee (billed by the DMS vendor) | $200 to $800/month |
| Implementation and data migration | $5,000 to $40,000 one time |
| Training and change management | $3,000 to $15,000 |
| A2P messaging and carrier fees | $100 to $600/month |
| Equity mining, if not native | $800 to $2,000/month |
| Dedicated CRM administrator | 0.25 to 1.0 FTE |
The administrator line kills more CRM implementations than the software does. A CRM without an owner reverts to a contact list within two quarters.
How to Choose an Automotive CRM: A Seven-Step Selection Sequence
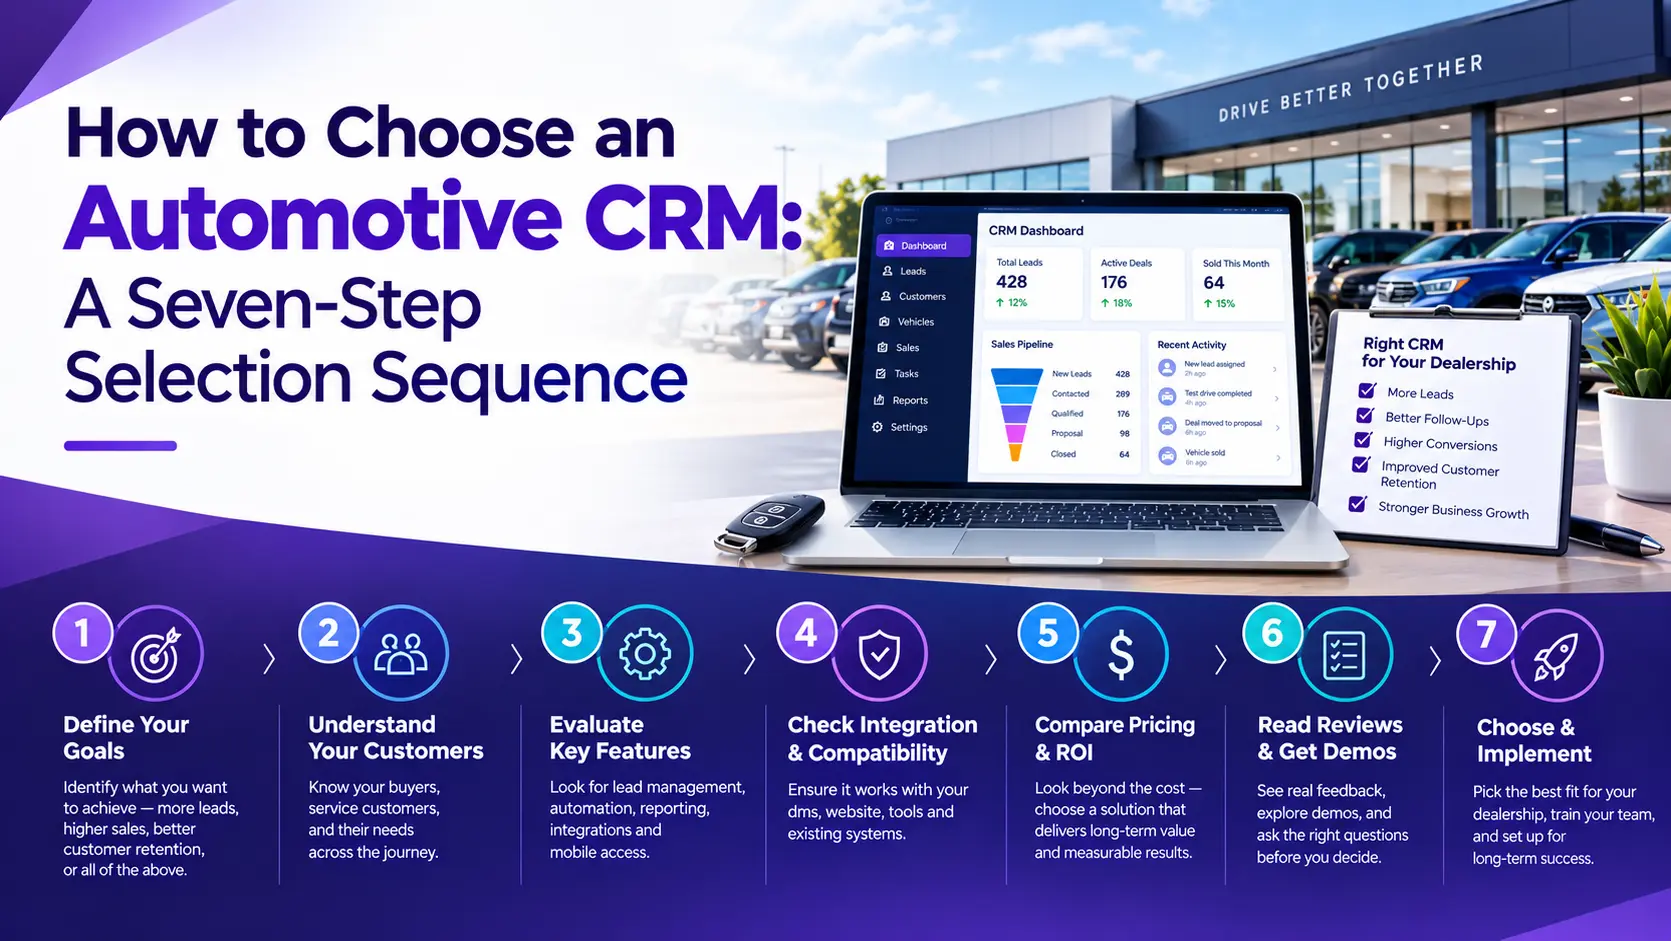
1. Confirm Your DMS and Its Certified Interface List
In writing, with the monthly data-access fee stated.
2. Decide Native or Horizontal
Retail rooftops need dealership-native. OEM, distributor, and fleet operations need horizontal.
3. Identify Your Binding Constraint
Adoption failure points to DriveCentric. Reporting depth points to VinSolutions. Enterprise BDC on CDK points to Elead. Special finance points to ProMax. Budget and simplicity point to AutoRaptor.
4. Test With Three Real Salespeople for Two Weeks
Not a demo. A sandbox with your actual lead volume.
5. Audit Compliance
SOC 2 Type II, encryption, MFA, 10DLC handling, data export terms.
6. Cost the Full Three Years
Include the administrator.
7. Name the Owner Before You Sign
A specific person, with the responsibility in their job description.
Automotive CRM and DMS Integration Services From Tech Implement
We do not sell a dealership CRM. We implement Microsoft Dynamics 365 and Salesforce for OEM importers, distributor networks, and dealer groups that need a customer data layer above the rooftop CRM, and we integrate those platforms with DMS environments through Fortellis, RCI, and custom middleware.
If you are choosing a rooftop CRM, this guide should get you there without us. If you are consolidating customer data across brands, rooftops, or non-retail lines of business, that is the problem we solve.
Prople Also Ask

No single platform wins across store types. VinSolutions leads franchise groups inside the Cox Automotive ecosystem. CDK Elead leads for enterprise groups running CDK Drive. DriveCentric leads on salesperson adoption. AutoRaptor leads for independents on verified review volume. ProMax leads for special finance.
A DMS runs the business: inventory, accounting, parts, service scheduling, payroll, and regulatory reporting. A CRM runs the customer relationship: leads, follow-up, appointments, and sales process.
The DMS is the system of record. The CRM is the system of engagement. They must exchange data, which is why integration depth decides the CRM choice.
A retail rooftop should not. Neither parses ADF leads natively, desks a deal, or mines equity against service history. Salesforce Automotive Cloud is the exception, and it targets OEM and captive finance operations rather than single rooftops. HubSpot works well as a marketing layer running alongside a dealership CRM.
Dealership-native platforms sell per rooftop, and reported street pricing runs $500 to $3,000 per rooftop per month. AutoRaptor sits at the lower end with unlimited users. VinSolutions, Elead, and ProMax sit at the upper end.
Add DMS data-access fees, implementation, and messaging costs on top.
Yes, once you exceed roughly 25 units a month or two salespeople. Below that, follow-up discipline substitutes for software. Above it, leads get lost, and the lost gross exceeds the license cost within one month.
ADF (Auto-lead Data Format) is the XML standard that marketplaces, OEM lead programs, and your website use to deliver leads.
A CRM that parses ADF natively populates the correct fields, deduplicates against existing customers, and routes by source. A CRM that does not will drop vehicle-of-interest data and break your source attribution reporting.
Equity mining reads DMS service history, original deal terms, and current lender payoff to identify customers in a position to upgrade. It generates sales from your existing customer base rather than from purchased leads.
VinSolutions, Elead, DealerSocket Revenue Radar, and ProMax Deal Finder include it. Other platforms integrate AutoAlert.